Motive, the AI platform for physical operations, has secured $1.3 billion in growth financing from General Catalyst’s Customer Value Fund and withdrawn its S-1 IPO registration statement filed with the SEC. The move signals that Motive—once on track to become a public company in 2026—has chosen to remain private to maximize runway for AI product development and geographic expansion.
The funding follows a $150 million Series D led by Kleiner Perkins in July 2025, bringing Motive’s total funding to over $700 million. With $600 million in annual recurring revenue growing 30% year-over-year, Motive has achieved the revenue scale of a mature public company while maintaining the operational flexibility of a private one.
Motive Funding & Valuation By CREDX Media
| Startup | Motive |
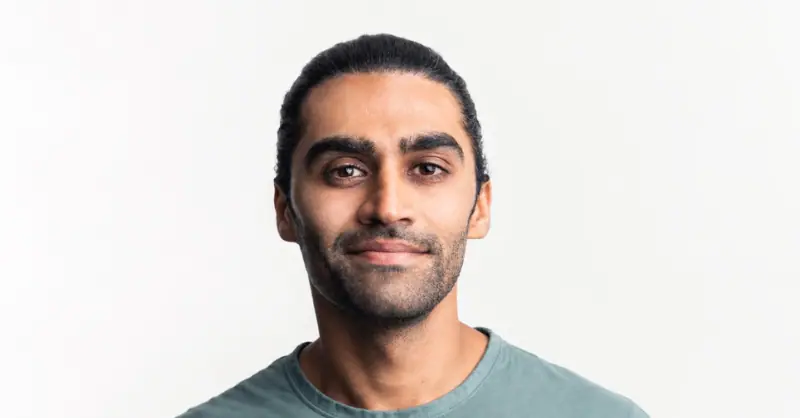
| Founder | Shoaib Makani |
| Founded | 2013 (as KeepTruckin) |
| Rebranded | 2021 (as Motive) |
| Latest Round | $1.3B (Series Growth) |
| Lead Investor | General Catalyst (Customer Value Fund) |
| Total Funding Raised | $700M+ |
| Last Known Valuation (2022) | $2.85B |
| Current Estimated Valuation | $3-4B+ (implied by growth round size) |
| Annual Recurring Revenue | $600M+ |
| ARR Growth Rate | 30% year-over-year |
| Large Customer ARR Growth | 60% YoY (customers >$100k/year) |
| Net Revenue Retention | 120%+ (for large customers) |
| Total Customers | ~100,000 across all segments |
| Customer Segments | Transportation, Construction, Energy, Field Service |
| Headquarters | San Francisco, USA |
| Category | Fleet Management AI, Physical Operations Intelligence |
Startup Overview: Motive
What Motive Is Building in Simple Words
Motive is an operating system for companies that run vehicles, equipment, and field crews. It combines data from dozens of sources—vehicle telematics, dashcams, maintenance records, fuel spend—into one AI-powered platform.
Here’s what Motive actually does:
1. AI Dashcams for Safety
- Mounted cameras in vehicles record driver behavior in real-time
- AI flags unsafe driving patterns (harsh braking, distracted driving, speeding)
- Alerts drivers and fleet managers to prevent collisions before they happen
- Virginia Tech Transportation Institute study found Motive’s AI dashcams catch risky behavior more consistently than competitors like Samsara and Lytx
2. Predictive Maintenance Tracking
- Monitors vehicle health through OBD sensors
- Predicts maintenance needs before breakdown occurs
- Automatically schedules service appointments
- Reduces unplanned downtime by 30-40%
3. Spend Management & Analytics
- Tracks fuel, tolls, maintenance, and insurance costs
- Provides per-mile cost breakdowns by vehicle
- Identifies inefficiencies and cost-saving opportunities
- Integrates with accounting systems
4. Field Crew Optimization
- GPS tracking for field service teams
- Route optimization to reduce idle time
- Time tracking and productivity analytics
- Compliance reporting for regulations
5. Maintenance and Operations Intelligence (Forthcoming)
- Next-generation tool combining all data streams
- Autonomous agents that handle routine maintenance scheduling
- Predictive analytics for fleet-wide optimization
Why Motive Matters
1. The Physical Operations Market Is Massive The physical operations software market was valued at $37.7 billion in 2026 and is projected to reach $179.6 billion by 2036—a 16.9% compound annual growth rate. That’s a $140+ billion market opportunity.
2. Motive Has Proven Monetization With $600M+ in ARR and 30% year-over-year growth, Motive isn’t a speculative startup. It’s a revenue-generating machine with unit economics that work at scale. Large customers (spending >$100k/year) are growing their spend by 60% annually, indicating strong product-market fit and expansion selling.
3. Network Effects in Operations Data Every vehicle Motive monitors generates data. Every field crew tracked creates historical patterns. This data trains Motive’s AI models, making safety predictions more accurate and maintenance forecasts more reliable. Competitors starting fresh can’t match 13 years of operational intelligence.
4. Customer Retention Is Exceptional Net revenue retention above 120% for large customers means existing customers are spending more each year without churn. This creates predictable, compounding revenue that public markets prize.
5. AI Dashcams Are the New Standard Vehicle safety regulations are evolving. Fleet operators are being held liable for driver behavior. AI dashcams that prevent collisions and document incidents are becoming table-stakes, not optional. Motive is benefiting from this shift.
Our Take on Motive
Motive is the infrastructure layer for the physical economy’s digital transformation.
The genius of Motive’s positioning is that it doesn’t replace existing vendors—it integrates with them. It connects to fuel cards, insurance systems, maintenance providers, and accounting software. This makes Motive stickier: removing it requires ripping out integrations across the entire operations stack.
The decision to withdraw its IPO filing and accept $1.3B from General Catalyst’s Customer Value Fund is strategic: Motive gets capital to invest in AI (particularly the forthcoming Maintenance and Operations Intelligence tool) without quarterly earnings pressure. General Catalyst’s fund, which also backed Grammarly, is known for backing revenue-predictable companies—exactly what Motive is.
The valuation jump (estimated $3-4B+ from $2.85B in 2022) is justified on fundamentals: $600M+ ARR at 30% growth with 120%+ net revenue retention is textbook SaaS playbook. At IPO, Motive could command $8-12B valuation easily. By staying private for 1-2 more years and hitting $1B ARR, Motive could IPO at $20B+ valuation.
Founder Background: From Truck Driver Pain to Fleet AI Empire
Shoaib Makani (Founder & CEO) started Motive in 2013 with a simple observation: truck drivers in California’s I-5 corridor were using paper logs and outdated technology to track driving hours.
Federal regulations (Hours of Service rules) require trucking companies to log driver hours for safety and compliance. Yet the tools available to drivers were primitive. Makani saw the inefficiency and built KeepTruckin as a solution.
Speaking about Motive’s evolution and why staying private made sense, Makani said:
“We’re building the intelligence layer for the physical economy. For our customers, that means preventing collisions, avoiding downtime, and eliminating manual work.”
This statement captures Motive’s evolution: it started as logging software, pivoted to fleet management when it recognized the bigger opportunity, and is now positioning itself as the intelligence layer—AI and data infrastructure—for all operations with moving assets.
The Evolution: From ELDs to Physical AI
2013: KeepTruckin launches Electronic logging device (ELD) software for trucking compliance. Solves the immediate pain point of regulatory compliance.
2019-2020: Expansion into dashcams and maintenance Recognizes that compliance is table-stakes. The real value is in safety and efficiency. Adds AI dashcams and predictive maintenance.
2021: Rebrands to Motive KeepTruckin name no longer captures scope. Motive reflects the new positioning: moving operations intelligence for any company with vehicles or field crews.
2022-2025: Goes multivertical Expands from trucking (transportation) into construction (equipment), energy (fleet management), and field service (utilities, HVAC, plumbing). Same platform logic works across industries.
2025-2026: AI-first approach Doubles down on AI—dashcam intelligence gets better, maintenance prediction gets predictive, operations optimization becomes autonomous. Sets up for IPO or strategic acquisition at premium valuation.
Insights: Why Physical AI Gets Patient Capital
The IPO Withdrawal as Strategic Patience
Motive had JPMorgan, Citigroup, Barclays, and Jefferies lined up as bookrunners for an NYSE listing under ticker “MTVE.” It chose to withdraw instead.
Why?
1. Valuation Flexibility Public markets trade off current multiples. Motive is growing 30% ARR annually with 120%+ net revenue retention—premium SaaS metrics. But IPO investors might demand near-term profitability or worry about competition (Samsara is public at $20B). By staying private, Motive avoids that discount.
2. AI Investment Runway Building proprietary AI models (predictive maintenance, autonomous agents, collision prevention) requires sustained investment. Public company pressure for quarterly profits could squeeze R&D budgets. Private with $1.3B capital means 2-3 years of AI-first strategy without earnings pressure.
3. Competitive Positioning Samsara (the only other major player in fleet management) is public at $20B valuation with $1B+ ARR. If Motive IPOs at current $3-4B valuation with $600M ARR, it looks cheap on multiple. Better to grow to $1B ARR, then IPO at $15-20B. The optionality is worth the wait.
General Catalyst’s Customer Value Fund Signal
General Catalyst’s Customer Value Fund previously invested $1 billion into Grammarly, a company with strong unit economics and predictable revenue. Their participation in Motive signals: “We believe this is a generational platform in physical operations.”
Pranav Singhvi, General Catalyst managing director, said:
“The physical AI market, and edge AI specifically, represents one of the most compelling long-term opportunities we see today.”
Translation: General Catalyst is betting on AI-native software for physical operations becoming the industry standard. Motive is positioned to own that category.
Competitive Landscape: Breadth vs. Point Solutions
Samsara (public, $20B valuation) is the closest competitor—also does fleet safety and operations. But Samsara focuses primarily on safety and compliance. Motive’s breadth (safety, maintenance, spend, field ops, and coming Maintenance and Operations Intelligence) is broader.
Geotab (private, Canadian, telematics specialist) focuses on vehicle telematics data and aftermarket integrations. Narrower than Motive.
CameraMatics (Dublin, raised €49M) does AI fleet safety. Point solution.
Tenderd (Dubai, $30M Series A) does AI analytics for fleet operations. Point solution.
Motive’s thesis: One integrated platform beats multiple point solutions. Integration creates stickiness, switching costs, and network effects in data.
Founder Intelligence: What Founders Can Learn from Motive
1. Start Solving a Real Problem, Then Expand
Motive started solving electronic logging device compliance for trucking. It didn’t try to build “operations OS” from day one. It solved one pain (compliance), proved economics work, then expanded (dashcams, maintenance, spend management, field service).
Lesson: Nail one vertical before going multivertical. Motive’s approach—starting with trucking, then expanding to construction, energy, field service—is methodical and defensible.
2. Revenue Clarity Attracts Premium Capital
Motive didn’t need to hype growth rates or TAM projections. It showed $600M ARR, 30% YoY growth, and 120%+ NRR. That clarity attracted General Catalyst. Point solutions raising small rounds on hype pale in comparison.
Lesson: Build for revenue, not just growth. Growth + profitability/unit economics is the SaaS winning formula.
3. Being a Platform Creates Defensibility
Motive integrates with accounting systems, fuel cards, insurance platforms, and telematics providers. This integration moat means customers can’t switch without ripping out their entire ops tech stack.
Lesson: Make yourself hard to leave. Integration, data network effects, and workflow centralization create defensibility.
4. IPO Timing Is a Strategic Choice, Not a Milestone
Motive had a clean path to IPO. Instead, it chose to stay private longer to invest in AI. This signals founder confidence: “We know we’ll go public. We’re choosing to optimize for long-term value, not medium-term exit.”
Lesson: IPO is a financing option, not a goal. Use it when it makes financial sense, not when investors pressure you.
5. Being Hardware-Adjacent Creates Advantage
Motive’s dashcams, sensors, and GPS devices generate continuous data streams that train ML models. This hardware-software loop is hard to replicate for pure software competitors.
Lesson: If you can own hardware touchpoints, do it. The data and defensibility compound over time.
Investor Intelligence: Why General Catalyst Leads
General Catalyst is known for backing growth-stage, revenue-predictable software companies. Their thesis: high-growth, profitable (or near-profitable) software businesses that have achieved PMF and are capital-efficient.
This is distinct from traditional venture (betting on category creation) or growth equity (betting on scaling existing categories). General Catalyst bets on founders who’ve proven the business model and are now capital-constrained.
Motive fits perfectly:
- Proven model: $600M ARR with 30% growth
- Predictable revenue: 120%+ NRR shows customers expand spending
- Large customers sticky: 60% YoY growth in large customer ARR
- Clear TAM: $179B physical operations market
General Catalyst’s participation validates that institutional capital sees Motive as a generational infrastructure play.
The Road Ahead for Motive
Expansion Targets
With $1.3B in capital and $600M+ ARR, Motive will target:
- $1B+ ARR within 18-24 months (requires 40-50% growth maintenance)
- International expansion (UK, Europe, Australia)
- Vertical expansion (utilities, waste management, agriculture)
- Autonomous operations agents (Maintenance and Operations Intelligence tool launch)
Product Roadmap (Expected)
- Maintenance and Operations Intelligence – AI agents that autonomously schedule maintenance, optimize routes, predict failures
- Predictive Safety – ML models that predict driver risk 24 hours in advance
- Financial Integration – Direct accounting system integration (QuickBooks, Sage, NetSuite)
- Autonomous Dispatch – AI that assigns jobs to field crews based on real-time location, skill, and capacity
- Sustainability Metrics – Carbon emissions tracking and reduction recommendations
Competitive Response
Expect:
- Samsara to accelerate maintenance and spend management offerings
- Geotab to build integrations with broader operations tools
- New startups to emerge in vertical-specific solutions (construction fleet AI, energy fleet AI)
- Microsoft, Google, Amazon to potentially enter with enterprise operations platforms
Motive’s moat: customer relationships + data network effects + AI capabilities trained on 13 years of operational data.
The Strategic Question: Why Withdraw IPO?
The TechFundingNews article notes the strategic ambiguity: Is Motive withdrawing IPO because it doubts public markets would reward an AI-fleet story, or is it simply buying more runway before facing quarterly earnings calls?
The answer is probably both:
- Valuation optimization – Growing to $1B ARR before IPO maximizes per-share value for founders and employees
- AI runway – Launching Maintenance and Operations Intelligence tool as a public company makes the growth story clearer
- Market conditions – Public market appetite for SaaS has cooled. Staying private for 1-2 years lets market normalize before IPO
The real test: Can Motive grow from $600M to $1B ARR in 18-24 months while maintaining 30%+ growth? If yes, IPO at $15-20B valuation makes sense. If growth slows to 15-20%, Motive might stay private longer.
Conclusion
Motive’s decision to raise $1.3B from General Catalyst and withdraw its IPO filing represents a sophisticated strategic choice: optimize for long-term value creation rather than medium-term liquidity.
With $600M+ in ARR, 100,000 customers, and AI capabilities trained on 13 years of operational data, Motive has established itself as the leading platform for fleet and operations management. The physical operations market is projected to grow from $37.7B to $179.6B by 2036—a $140B opportunity—and Motive is positioned to capture significant market share.
Whether Motive remains private for 2-3 more years before an IPO at premium valuation, or becomes an acquisition target for a larger software company seeking to build operations infrastructure, is the question its next 18 months will answer. Either way, Motive has proven that physical operations AI is not a point solution category—it’s enterprise infrastructure that commands institutional capital and premium valuations.
For deep analysis of fleet management, physical operations AI, and the companies building infrastructure for the physical economy, explore CREDX Media for comprehensive coverage of startup funding trends and founder intelligence.
Frequently Asked Questions
1. What does Motive do exactly?
Motive is a software platform for companies that manage vehicles, equipment, and field crews. It combines AI dashcams, vehicle telematics, predictive maintenance, spend tracking, and field crew optimization into one integrated system. Users can monitor driver safety in real-time, predict maintenance needs before breakdowns, track operational costs, and optimize routes for field service teams.
2. How much did Motive raise in this funding round?
Motive raised $1.3 billion in growth financing from General Catalyst’s Customer Value Fund. This is part of Motive’s Series growth round (not a traditional Series A/B/C). Total funding raised by the company exceeds $700 million across all rounds.
3. Who is Motive’s founder?
Motive was founded in 2013 by Shoaib Makani as KeepTruckin, an electronic logging device (ELD) solution for trucking compliance. The company rebranded to Motive in 2021 as it expanded beyond logging into fleet management, safety, and operations intelligence across multiple verticals.
4. How much revenue does Motive generate?
Motive generates over $600 million in annual recurring revenue (ARR) and is growing 30% year-over-year. For large customers spending more than $100,000 annually, Motive’s ARR is growing 60% year-over-year, demonstrating strong expansion selling within existing customers.
5. Why did Motive withdraw its IPO filing?
Motive withdrew its S-1 registration statement and planned NYSE listing (ticker “MTVE”) to remain private longer. The strategic rationale: staying private allows Motive to invest heavily in AI product development without quarterly earnings pressure, and gives the company time to grow from $600M to $1B+ ARR before IPO, which would maximize valuation and per-share value.
6. What is Motive’s valuation?
Motive’s last known valuation was $2.85 billion in 2022. The company has not disclosed a current valuation with this funding round. Based on the $1.3B raised and market comparables (Samsara at $20B with $1B+ ARR), Motive’s estimated current valuation is $3-4B+.
7. How many customers does Motive serve?
Motive serves approximately 100,000 customers across transportation, construction, energy, and field service sectors. The company’s largest customers (spending over $100k annually) are its fastest-growing segment, expanding spending by 60% year-over-year.
8. What is net revenue retention (NRR), and why does Motive’s 120%+ matter?
Net revenue retention measures how much revenue from existing customers is retained and expanded within a year. A 120%+ NRR means Motive’s existing customer base is spending 20% more each year (from expansion) without churn. This signals strong product-market fit and is why institutional investors like General Catalyst back Motive.
9. Who are Motive’s main competitors?
Samsara (public at $20B valuation) is Motive’s closest competitor in fleet management. Geotab is a Canadian telematics specialist. Narrower competitors include CameraMatics (AI fleet safety, €49M raised) and Tenderd (AI fleet analytics, $30M Series A). Motive differentiates through breadth—one integrated platform vs. point solutions.
10. What is the Maintenance and Operations Intelligence tool, and when launches?
Maintenance and Operations Intelligence is Motive’s next-generation product combining all data streams (safety, maintenance, spend, crew tracking) with AI agents to autonomously handle routine maintenance scheduling, predict equipment failures, and optimize operations. Launch timeline not disclosed, but funding will accelerate development.
Executive Discussion & Contributions
No executive dispatches on this briefing yet
Join the conversation above. Share your thesis, legal nuance, or empirical observations.