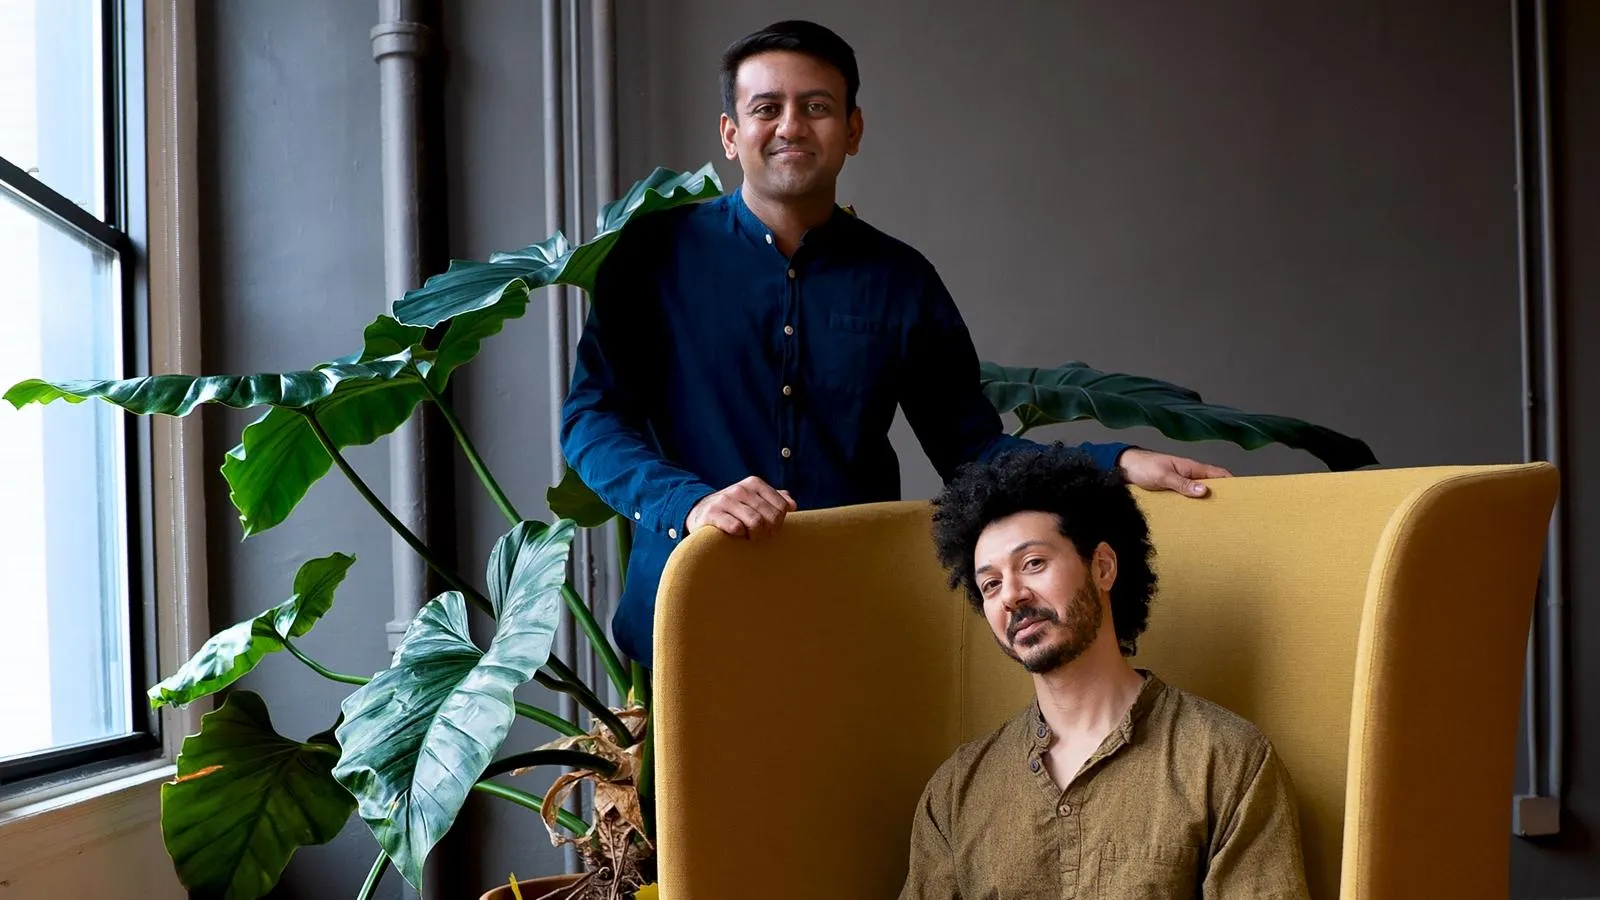
Clay the New York-based go-to-market startup platform, has raised $115 million in Series D funding led by Wellington Management, achieving a $7.1 billion valuation. The round marks a stunning 2.3x valuation increase in just over a year, signaling institutional investor confidence that AI-powered GTM infrastructure is the next trillion-dollar platform layer.
The funding comes after Clay closed a $100 million Series C at $3.1 billion valuation just over a year ago, followed by a $5 billion employee tender offer in January 2026. This rapid re-rating reflects market recognition that Clay isn’t just building another sales tool—it’s constructing the operating system for revenue teams in the AI era.
Clay Financials By CREDX Media
| Startup | Clay |
|---|---|
| Founders | Kareem Amin, Nicolae Rusan, Varun Anand |
| Raised (Series D) | $115M |
| Total Funding Raised | $300M+ (Series A through Series D) |
| Current Valuation | $7.1B |
| Previous Valuation (Series C) | $3.1B |
| Valuation Growth | 2.3x in 13 months |
| Stage | Series D |
| Lead Investor (Series D) | Wellington Management |
| Other Investors | Sequoia Capital, StepStone, Andreessen Horowitz, Perennial, Meritech, DST, CapitalG, BoxGroup, Boldstart, Bloomberg Beta, Evolution Equity Partners |
| Customers | 17,000+ (including Anthropic, Google) |
| Headquarters | New York, USA |
| Founded | 2017 |
| Category | Go-to-Market (GTM) AI, Sales Intelligence |
Startup Overview: Clay
What Clay Is Building in Simple Words
Clay is transforming how sales and marketing teams find, understand, and engage with customers through AI agents.
Here’s how it works:
1. Data Aggregation Layer
- Pulls together CRM records, product usage data, campaign engagement metrics, call records, and email history
- Layers in external signals: funding announcements, hiring activity, company news, job postings
- Creates a unified 360-degree view of each prospect and customer
2. AI Agent Intelligence
- Uses machine learning to identify which prospects are sales-ready
- Predicts the next best action for sales reps to take
- Generates personalized outreach copy based on prospect research
- Orchestrates multi-channel campaigns across email, LinkedIn, and custom channels
3. Autonomous Execution
- AI agents can identify fintech marketing leaders, research their companies, draft personalized outreach, and launch campaigns automatically
- System learns from campaign performance and optimizes future outreach
- Reps see recommendations for what to do next, reducing guesswork
4. Go-to-Market Infrastructure
- Replaces disconnected point solutions (data tools, email platforms, CRM systems) with integrated GTM platform
- Treats revenue teams the way development teams are treated: as engineers with tools, not manual workers
Why Clay Matters
1. AI Is Making Sales Automatable. Traditional sales processes relied on human intuition, cold calling, and manual research. AI agents can now handle 80% of the research and prospecting work, freeing reps to focus on closing and relationship building.
2. The GTM Market Is Massive and Underfunded. The global AI-in-sales market was worth $50.8 billion in 2026 and is projected to reach $383 billion by 2034—a 7.5x expansion in less than a decade. Yet most GTM tools are still built for the pre-AI era.
3. Clay Is Capturing Multiple Revenue Streams
- Subscription revenue from GTM teams
- Data licensing from aggregated prospect intelligence
- Agent-as-a-service (companies pay for automated campaigns)
- Enterprise integrations (API revenue)
4. Network Effects in Data Every time Clay processes a prospect, it gathers data that makes its AI models smarter. More customers = more data = better predictions. This creates a compounding advantage competitors struggle to replicate.
Our Take on Clay
Clay isn’t a sales tool—it’s the infrastructure layer that makes AI-native go-to-market possible.
The distinction is critical. Point solutions (email, LinkedIn automation, lead databases) optimize individual tasks. Clay optimizes the entire GTM workflow. That’s why Wellington Management led this round: late-stage institutional investors recognize category-defining platforms when they see them.
The valuation jump from $3.1B to $7.1B in 13 months seems aggressive until you consider the TAM expansion. If the AI-in-sales market grows from $51B to $383B by 2034, and Clay captures even 2-3% market share, the company could be worth $8-10 billion at IPO—making a $7.1B current valuation attractive on forward multiples.
The real test: Can Clay expand beyond early-adopter tech companies (Anthropic, Google) to traditional enterprises? That’s where true scale happens.
Founder Background: From No-Code Dreams to GTM Dominance
Clay’s story begins with two founders who met at McGill University and later worked together at Microsoft: Kareem Amin and Nicolae Rusan.
Kareem Amin (CEO) Amin was born in Egypt and raised in a community of expat hospital workers in Saudi Arabia. He studied electrical engineering in Canada (McGill University), later moved to the US, and worked as a software engineer at Microsoft. His vision was to make programming accessible to people without coding skills.
Speaking about Clay’s mission and the Series D, Amin said:
“AI is unleashing the biggest wave of company creation in history, and Clay’s goal is to be the engine those companies use to grow to their full potential. We started by aggregating the best data for B2B companies. Then we built the infrastructure to run any personalised campaign on top of it. Now we’re building agents that can help grow your company for you.”
This statement reveals Clay’s evolution: it didn’t start with sales tools. It started with data aggregation, pivoted to campaign infrastructure, and now is pivoting to agents. That willingness to evolve based on customer demand is a founder quality that inspires investor confidence.
Nicolae Rusan (Co-Founder) Rusan, who also met Amin at McGill and worked alongside him at Microsoft, brings technical depth to the co-founder dynamic. While specific details on his background are less public, his presence signals that Clay is a engineer-first company, not a sales-first company playing with technology.
Varun Anand (Co-Founder) Anand joined as the third co-founder in 2021 as Clay pivoted toward go-to-market teams specifically. This timing is critical: the market was just beginning to recognize that AI could automate sales workflows. Anand’s addition brought GTM expertise that shaped the company’s commercial positioning.
The Evolution of Clay: From No-Code to AI Agents
2017: The No-Code Vision
Amin and Rusan started with a simple idea: build tools that let non-technical people write code. This is a classic “first idea is wrong” startup story.
2019-2020: Pivot to Data Aggregation
After realizing no-code wasn’t the real problem, Clay pivoted to B2B data aggregation. The company started pulling together business data from multiple sources—firmographics, hiring signals, funding announcements—to create prospect intelligence.
2021: Anand Joins, GTM Focus Emerges
With Varun Anand’s addition, Clay doubled down on go-to-market teams. Instead of being a general data tool, it became the data infrastructure for sales and marketing.
2023-2024: Campaign Orchestration
Clay added workflow automation—the ability to create and execute multi-step campaigns. This is when investors really took notice. The company had found product-market fit.
2025-Present: AI Agents
Now Clay is building autonomous agents. Sales teams describe what they want to accomplish (“find and engage fintech marketing leaders in funded companies”), and Clay’s agents handle research, personalization, and execution.
Insights: What Does This Valuation Really Mean?
Why AI-in-Sales Infrastructure Gets Premium Valuations
Wellington Management’s decision to lead at $7.1B reveals institutional thinking: AI-native GTM is a category moment, not a point product.
Historical precedent: Salesforce (CRM), HubSpot (inbound marketing), and Marketo (automation) all became $10B+ companies by being the operating system for their respective functions. Clay is positioning itself as the operating system for GTM in the AI era.
The Competitive Landscape Is Heating Up
Regie.ai raised a $30 million Series B in February, bringing its total to over $50 million. It’s building AI-powered sales strategy recommendations.
11x (which builds fully autonomous “digital workers” rather than a workflow layer) has raised roughly $76 million since its Benchmark-led Series A. It’s going after the “replace the SDR” thesis head-on.
Established players like Apollo.io and ZoomInfo remain entrenched but are legacy data providers, not AI-native platforms.
Clay’s argument: It’s not replacing one job title (like 11x replaces SDRs). It’s providing infrastructure that makes the entire GTM function smarter and more efficient.
What the $1M GTM Engineer Fund Signals
Alongside the Series D, Clay announced a $1 million fund to train “GTM engineers”—a job title Clay popularized. The fund is educational: Clay wants to create a career path and ecosystem around the role.
This is genius positioning. By creating and funding a career track, Clay is:
- Building a community of users who are trained on Clay’s platform
- Signaling that “GTM engineer” will be a major job title going forward (like “DevOps engineer” today)
- Creating advocates who will pitch Clay internally when they get hired at new companies
Founder Intelligence: What Founders Can Learn from Clay
1. Multiple Pivots Are Okay—As Long As You’re Solving Real Problems
Clay pivoted from no-code to data to campaigns to agents. Each pivot solved a customer problem more directly than the last. Founders often think pivoting is failure. Clay proves it’s evolution.
Lesson: Chase customer demand, not your original idea.
2. The Founding Team Matters More Than the Idea
Amin and Rusan met at McGill, worked together at Microsoft, and had been collaborating for years before starting Clay. Investors weren’t betting on “AI agents for sales”—they were betting on Amin + Rusan + Anand executing at scale.
Lesson: Spend more time on co-founder fit than on perfecting your pitch deck.
3. Timing the Market Is Everything
Clay launched data aggregation when AI was nascent. By 2023, when it pivoted to agents, large language models were mature enough to make autonomous agents practical. Had Clay launched agents in 2017, the infrastructure didn’t exist.
Lesson: Sometimes “wrong” timing on an idea is actually perfect timing if you’re building the foundations.
4. Build for Ecosystems, Not Just Customers
Clay’s GTM Engineer fund isn’t a marketing expense—it’s ecosystem-building. By creating a career path and training program, Clay is building dependency on its platform at an educational level.
Lesson: The most defensible businesses build entire ecosystems around their platforms.
5. Raise Large Amounts Late
Clay didn’t beg for $2M seed rounds. It focused on proving product-market fit, then raised $100M Series C, then $115M Series D. Large later-stage rounds attract institutional investors and institutional talent.
Lesson: Better to have one large round from Wellington than five small rounds from dispersed angels.
Investor Intelligence: Wellington Management’s Late-Stage Confidence
Wellington Management is a $1+ trillion asset manager known for late-stage venture and growth equity investments. Their participation signals:
1. IPO Positioning: Late-stage institutional investors only lead rounds when they’re confident in exit paths. Wellington’s involvement suggests Clay could IPO within 2-3 years.
2. Public Markets Valuation: By leading at $7.1B, Wellington is saying: “We believe this company is worth $15-20B at IPO.” That’s aggressive but not unreasonable given the TAM and growth trajectory.
3. Category Validation: Wellington doesn’t lead rounds in emerging categories. Their participation validates that AI-in-sales is no longer emerging—it’s institutional.
The Road Ahead: What’s Next for Clay?
Growth Targets (Implied)
With $115M in fresh capital and 17,000+ customers, Clay will likely target:
- 30,000+ customers within 18 months
- $500M+ ARR (implied by $7.1B valuation)
- Expansion into enterprise (current base skews startup/mid-market)
- International expansion (primarily US-focused today)
Product Roadmap (Expected)
- Advanced Agent Capabilities – More autonomous decision-making, less manual configuration
- Vertical-Specific Solutions – Insurance GTM, FinTech GTM, Enterprise SaaS GTM
- API and Integrations – Embedding Clay into existing tech stacks (Salesforce, HubSpot, Marketo)
- Data Partnerships – Exclusive access to high-quality prospect data sources
- Compliance and Enterprise Security – HIPAA, SOC 2, enterprise SSO for large customers
The Competitive Response
Expect Salesforce, HubSpot, and other legacy platforms to:
- Launch in-house AI agent capabilities
- Acquire GTM AI startups
- Raise prices on existing customers while claiming “AI is included”
Clay’s moat: proprietary data + network effects + early-mover advantage with sophisticated GTM buyers.
The Bigger Picture: AI Agents as Infrastructure
Clay’s Series D isn’t just about selling more subscriptions. It’s about AI agents becoming a recognized category within enterprise software.
The progression:
- Spreadsheets (1980s-2000s) – Manual work, low scale
- SaaS Point Solutions (2000s-2015) – Workflow optimization, medium scale
- Integrated Platforms (2015-2024) – Cross-functional workflows, high scale
- AI Agents (2024-Present) – Autonomous decision-making, exponential scale
Clay is betting it can be the agent infrastructure for GTM, the way Salesforce was the CRM infrastructure in 2000.
Conclusion
Clay’s $115M Series D at $7.1B valuation reflects a fundamental shift in how companies approach go-to-market. The traditional GTM playbook—hiring SDRs, cold outreach, manual research, slow feedback loops—is becoming obsolete.
With 17,000+ customers already using its platform, including tech giants like Anthropic and Google, Clay has proven that AI agents can drive real business outcomes. Wellington Management’s late-stage participation signals that serious institutional capital believes Clay can become a $15-20B public company.
The real question isn’t whether Clay will scale—the product clearly works. The question is whether it can remain independent as larger software companies recognize the strategic value of AI-native GTM infrastructure and attempt to acquire or compete.
For now, Clay’s position is secure. It has capital ($115M), customers (17,000+), and team depth. The next 18 months will determine whether it becomes the Salesforce of the AI era or an important acquisition target for a larger platform.
For deep insights into AI-powered GTM, SaaS funding trends, and founder intelligence from the world’s most ambitious startups, explore CREDX Media for comprehensive analysis of the startup ecosystem and investment landscape.
Frequently Asked Questions
1. What exactly does Clay do?
Clay is a go-to-market platform that combines data aggregation, AI-powered insights, and autonomous agents to help sales and marketing teams identify prospects, research them, personalize outreach, and execute campaigns. It replaces multiple point solutions (databases, email tools, CRM systems) with an integrated platform.
2. How much did Clay raise in this Series D round?
Clay raised $115 million in Series D funding led by Wellington Management, achieving a $7.1 billion valuation. Previous backers Sequoia Capital, StepStone, Andreessen Horowitz, Perennial, Meritech, DST, CapitalG, BoxGroup, Boldstart, Bloomberg Beta, and Evolution Equity Partners all participated.
3. Who are Clay’s founders?
Clay was founded by Kareem Amin (CEO) and Nicolae Rusan in 2017. Varun Anand joined as the third co-founder in 2021 as the company pivoted toward go-to-market teams specifically. Amin was born in Egypt, raised in Saudi Arabia, and studied electrical engineering at McGill University before working at Microsoft.
4. How many customers does Clay have?
Clay serves 17,000+ customers, including major tech companies like Anthropic and Google. The customer base spans startups, mid-market, and enterprise segments, with particular strength among software companies and venture-backed startups.
5. What was Clay’s valuation in the Series C round?
Clay closed its Series C at a $3.1 billion valuation just over a year before this Series D. The jump to $7.1B represents a 2.3x increase in 13 months, reflecting accelerating revenue growth and market validation.
6. How do Clay’s AI agents work?
Clay’s AI agents use machine learning trained on aggregated prospect data and campaign performance to make autonomous decisions. Users describe what they want to accomplish (e.g., “find fintech marketing leaders in funded companies”), and agents handle research, personalization, and campaign execution, adjusting strategy based on real-time performance.
7. What is Clay’s GTM Engineer fund?
Alongside Series D, Clay announced a $1 million fund to train people for the “GTM engineer” job title it popularized. The fund supports educational programs and training to create a career path for revenue operations and sales engineering roles.
8. Who is Wellington Management?
Wellington Management is a $1+ trillion asset manager known for leading late-stage venture and growth equity investments. Their participation in Clay’s Series D signals institutional confidence in the AI-in-sales category and suggests potential IPO within 2-3 years.
9. What is the market size for AI-in-sales platforms?
The global AI-in-sales market was worth $50.8 billion in 2026 and is projected to reach $383 billion by 2034, according to Global Market Insights. This 7.5x expansion over less than a decade makes AI-native GTM a priority for venture investors.
10. What are Clay’s main competitors?
Competitors include Regie.ai (which raised $30M Series B), 11x (which has raised $76M for autonomous SDRs), Apollo.io (data provider), and ZoomInfo (legacy data platform). Clay differentiates by offering integrated GTM infrastructure rather than point solutions or job replacement.
Executive Discussion & Contributions
No executive dispatches on this briefing yet
Join the conversation above. Share your thesis, legal nuance, or empirical observations.